LIFESTYLE
How to Withdraw Money Without Spouse Knowing: Joint Account Rules
How to withdraw money without spouse knowing depends on the account: either joint owner may take the balance, yet a court can still require an accounting.

How to withdraw money without spouse knowing is a simpler bank question than it looks. On a typical joint checking account in the United States, the other owner’s signature is not required for a withdrawal or a closure.
The account agreement, state property law, and any divorce order can still require you to account for money the bank already paid out. The sections below match the name on the account, what one owner can do alone, and what to do if the money is already gone.
If you are in immediate danger, contact local emergency services before you move any funds, and use the safety contacts later on this page.
Whose Name Controls a Joint Account Withdrawal?
The bank follows the names on the account, not a marriage certificate. When your name is on a joint checking account, the bank treats you as an owner of the whole balance, including deposits your spouse made.
An account in your name alone does not give your spouse an owner’s right to empty it, and an account in your spouse’s name alone is not one this joint-account rule tells the bank to pay out to you. Taking money from an account that does not list you is a different act from using an account you already own.
| Whose name is on it | What the bank does with a withdrawal | What you still check |
|---|---|---|
| Both names, joint checking | In most circumstances, either owner can withdraw the full balance and close the account | The account agreement, state property law, and any court order |
| Your name only | You can withdraw. Your spouse is not an owner of that account | Community property or other marital rules that can still reach earnings inside it |
| Your spouse’s name only | The bank should not pay you from an account you do not own | Do not use the joint-account rule as a reason to take those funds |
The same bank rule applies to joint owners who are not married to each other. Marriage is the layer that adds property division and divorce orders, which come later on this page. A power of attorney is a separate paper from joint ownership, and banks often want that authority on their own form before an agent can act.
What Can One Owner Do on a Joint Account?
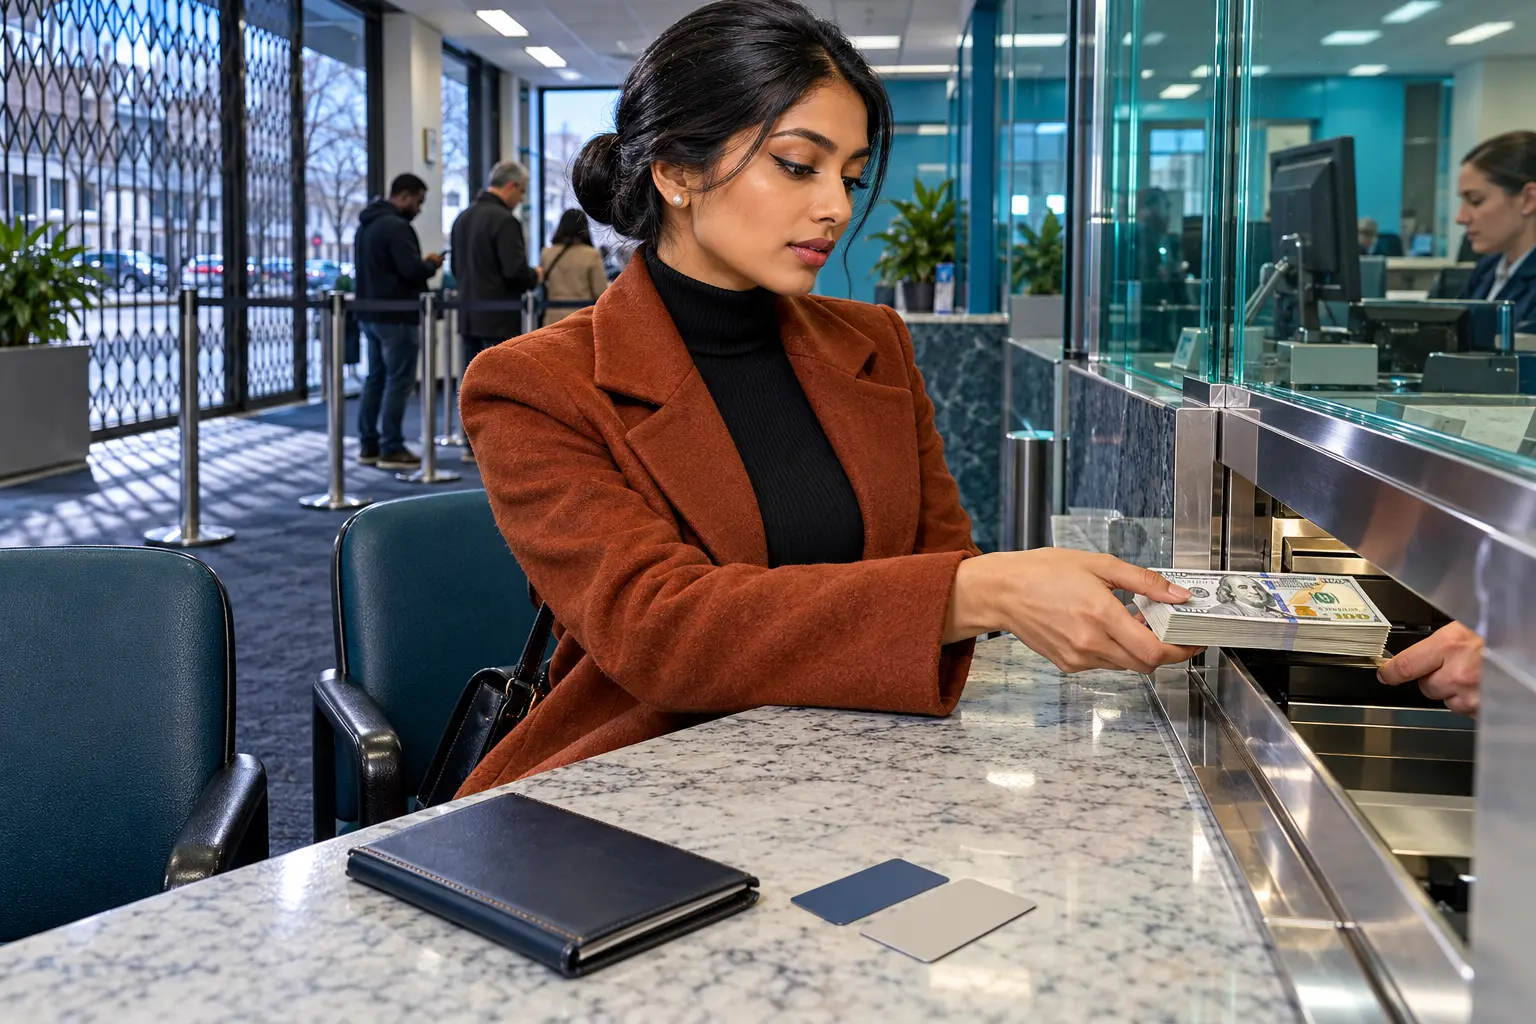
Once both names are on the account, a withdrawal, a closure, and a name change are three different requests. Your deposit agreement is the page that says which of them one person can make alone.
WHAT ONE OWNER CAN ASK THE BANK
- The withdrawal: In most circumstances, either person on a joint checking account can take money out without the other owner’s agreement.
- The closure: Closing is a separate request from emptying the balance, and a scheduled payment can still be presented until you move it.
- The name change: Taking the other person off, while leaving the account open, is harder than closing.
In most circumstances, either owner can withdraw and close a joint checking account, and you still match that answer to your own agreement because state law can add protection. In general, you need your spouse’s consent to remove them, and in most cases state law or the account terms block a removal they did not agree to, though some banks allow it.
Ask the bank for the agreement if you no longer have the copy you signed. Read the lines that name who may withdraw, who may close, and whether both people must sign. A balance of zero leaves the account open unless the bank closes it, so ask for written confirmation when you do close, the same way you would when you move a checking account and want proof the old one is shut.
How Does State Law Treat Money You Withdraw?
The law of the state you treat as your permanent home decides whether you have community property. For married taxpayers, IRS Publication 555, revised December 2024, names these nine community property states.
- Arizona
- California
- Idaho
- Louisiana
- Nevada
- New Mexico
- Texas
- Washington
- Wisconsin
Registered domestic partners who live in Nevada, Washington, or California fall under that same publication, because those states apply community property rules to them. If you live in Alaska, Tennessee, or South Dakota, do not assume the nine-state list covers you, because Publication 555 does not take up the community property election those states offer. IRS staff guidance also treats Guam and Puerto Rico as community property jurisdictions.
Moving the cash to an account in one name does not end the other spouse’s claim in a community property state. In the other states, community property is not the starting rule, and a divorce court can still divide property acquired during the marriage, so ask a lawyer there before you treat a transfer as finished.
When Does a Divorce Case Change the Rules?
The account agreement governs the bank until a court order says otherwise. After a divorce case starts, that order can limit what either of you does with joint money and with money in one name.
California writes the limit into the papers that open the case. Family Code section 2040 puts a restraining order in a divorce summons that bars both parties from transferring, concealing, or disposing of any property, including separate property, unless the other party agrees in writing or the court allows it.
- The order still allows spending in the usual course of business and for the necessities of life.
- It also allows community property, quasi-community property, or your own separate property to pay reasonable attorney’s fees and costs.
- Extraordinary spending needs notice to the other party at least five business days before you incur it, plus an accounting to the court.
That statute is California law. Other states use their own summons language, and some do not restrain property until a judge signs a separate order. Read every page of a summons already served on you before you withdraw, because a transfer the bank would still process can be the act the order forbids.
How to Open an Account in Your Name Only
If no court order stops you, and your name is on the joint account, the account a spouse cannot withdraw from tomorrow is one that does not carry their name. Bank staff who watch this at the counter see the same outcome over and over: a customer learns the other owner took the balance, and the teller cannot put it back. A joint account that holds household bills, plus a second account in your name for the rest, keeps either person from holding a key to every dollar.
If You Are Leaving Because of Abuse
Financial abuse shows up in nearly all cases of domestic violence, often as control of the account, an allowance, or a block on work or school. If you are in immediate danger, contact local emergency services. In the United States, the National Domestic Violence Hotline answers at 1-800-799-SAFE (7233), by text at START to 88788, and at TheHotline.org. Readers elsewhere can find a helpline in your country.
The National Network to End Domestic Violence publishes financial safety planning guidance you can use with an advocate who knows your situation. If it is safe, set aside extra income, however small, in a private account, and decide ahead of time what you will do if that savings is found.
- When you leave, consider taking at least half of any joint funds.
- The same guidance raises that share to 75% if you are leaving with children.
- Document how those funds were spent, open a separate bank account, change direct deposits, and change PINs.
Use those shares in the safety-planning situation that guidance describes, and expect to show what the money paid for. A court can still ask for that record. This page does not describe a way to keep a withdrawal invisible. Shared logins, mailed statements, and alerts already turned on are common ways a co-owner sees the transfer, and concealing property can violate a court order.
Steps to Move Your Pay to the New Account
For a move that is not an emergency exit, use a sequence that keeps bills from bouncing and leaves a record a lawyer can read.
- Check the account agreement for one-owner withdrawals, and read any divorce summons for a transfer ban.
- Write down every direct deposit and every automatic payment tied to the joint account.
- Open a checking account in your name only, and ask what identification and opening deposit the bank requires.
- File the direct-deposit change with your employer, learn the date of the first deposit into the new account, and switch automatic payments to that account after that date.
- Move the funds by electronic transfer, by a check you write, or by a cashier’s check, keep the statements, and leave enough in the joint account for debits that have not switched yet.
- If your agreement lets one owner close the joint account, close it only after those payments have moved, and ask the bank for written confirmation that it is closed.
Turn on balance alerts for the joint account if the bank offers them, so you see a later withdrawal on the day it happens. Ask whether the bank can require two signatures above a set amount. Expect both owners to have to accept that change, and do not treat it as a switch you can flip alone.
If Your Spouse Already Took the Joint Money
If your spouse’s name is on the joint account, the bank’s payment to them follows the same rule that would have applied to you. A complaint at the branch does not reverse a withdrawal the account agreement allowed, because the bank is not deciding a marriage dispute.
Save the statements that show the balance before the withdrawal, the amount, the date, and any fee that posted with it. Because a name comes off only with consent in most cases, open an account in your name and point your pay there so the next deposit is not sitting where the other owner can take it.
Bring those statements to a family lawyer if you need a court to account for the money, to set temporary support, or to restrict what is left. Keep paying necessities that remain in your name, and note every payment. That file is what you would want in hand if you were the one explaining a withdrawal.
Frequently Asked Questions
Does a Separate Account Make the Money Mine?
No. An account titled in your name does not by itself end a community property claim if you live in one of the nine community property states. Publication 555 is the IRS guide for married people domiciled there, and the law of the state you treat as your permanent home decides whether those rules apply. In the other states, community property is not the starting rule, and a divorce court can still divide property acquired during the marriage.
What If We Share an Account but Are Not Married?
The bank looks at the names on the account, not at a marriage license. In most circumstances either joint owner can withdraw the money and close the account whether or not you are married. Marriage adds community property rules and divorce-court orders on top of that bank rule. If you are unmarried and one owner takes more than they deposited, the bank will not rebuild the deposit history in order to reverse the withdrawal, and any payback is a dispute between the two owners.
Will Closing the Joint Account Cancel Joint Debts?
No. Closing a joint checking account does not remove your name from a joint loan, credit card, or other debt. A divorce decree can assign the bill to one spouse, and a debt collector can still contact anyone whose name remains on the debt until the creditor releases that person or the debt is refinanced into one name.
Can the Bank Freeze a Joint Account on My Request?
Do not count on a freeze. In general you need your spouse’s consent to take their name off, and in most circumstances either owner can still withdraw. Ask the bank what limits it can add, including a two-signature requirement, and expect both owners to have to accept that change. When your spouse will not agree and you need access cut off, a court order is what overrides the account agreement.
The agreement tells you whether one signature is enough, the summons tells you whether a court has already limited transfers, and the statement shows the amount and the date. Bring those three to a lawyer if the other owner disputes the move.
Disclaimer: This article is an educational guide to US joint checking accounts and the state and federal sources cited here, and it is informational only. It is not legal, financial, or tax advice, and it does not create a lawyer-client relationship. Talk with a lawyer licensed in your state, and with your bank about your own account agreement, before you withdraw, close, or move money. Hotline details, property rules, and account terms reflect those sources as reviewed and can change.

Final Fantasy Resonance Turns a Dead Gacha Into HD-2D

PHP2Shell Forced Sites Offline While Exploits Stalled

Kindle+ Folds AI Audiobooks Into the Page-Read Fund

Chip Stocks Fall as the Bond Rally Cheapens AI Spend

Comcast’s Record Odyssey Quarter Doubles as the Exit

Microsoft 365 Auth Fault Took Down Exchange and Teams

Xbox Caps Game Pass Cloud Gaming at 15 Hours

OpenAI Unveils GPT-6 Astra With a Critical Cyber Label

Squishy Dumpling Toys Recalled After Hiding Illegal Water Beads

OpenClaw 2.0 Ships a Team Workplace With Host-Trust Defaults
-
 NEWS3 months ago
Microsoft 365 Auth Fault Took Down Exchange and Teams
-
 GAMING2 months ago
Xbox Caps Game Pass Cloud Gaming at 15 Hours
-
 NEWS2 months ago
OpenAI Unveils GPT-6 Astra With a Critical Cyber Label
-
 NEWS3 months ago
OpenClaw 2.0 Ships a Team Workplace With Host-Trust Defaults
-
 LIFESTYLE2 months ago
Squishy Dumpling Toys Recalled After Hiding Illegal Water Beads
-
 BUSINESS2 months ago
Diesel Breaks Its Record as the White House Claims Credit
-
 BUSINESS2 months ago
ChargePoint Stock Rally Prices Wilmer’s Three-Year Cash Plan
-
 NEWS2 months ago
IFA 2026’s Weird Gadgets Are Building a Sensor Home