BUSINESS
Oura Pulls Its IPO and Stalls Forerunner’s Cash-Out
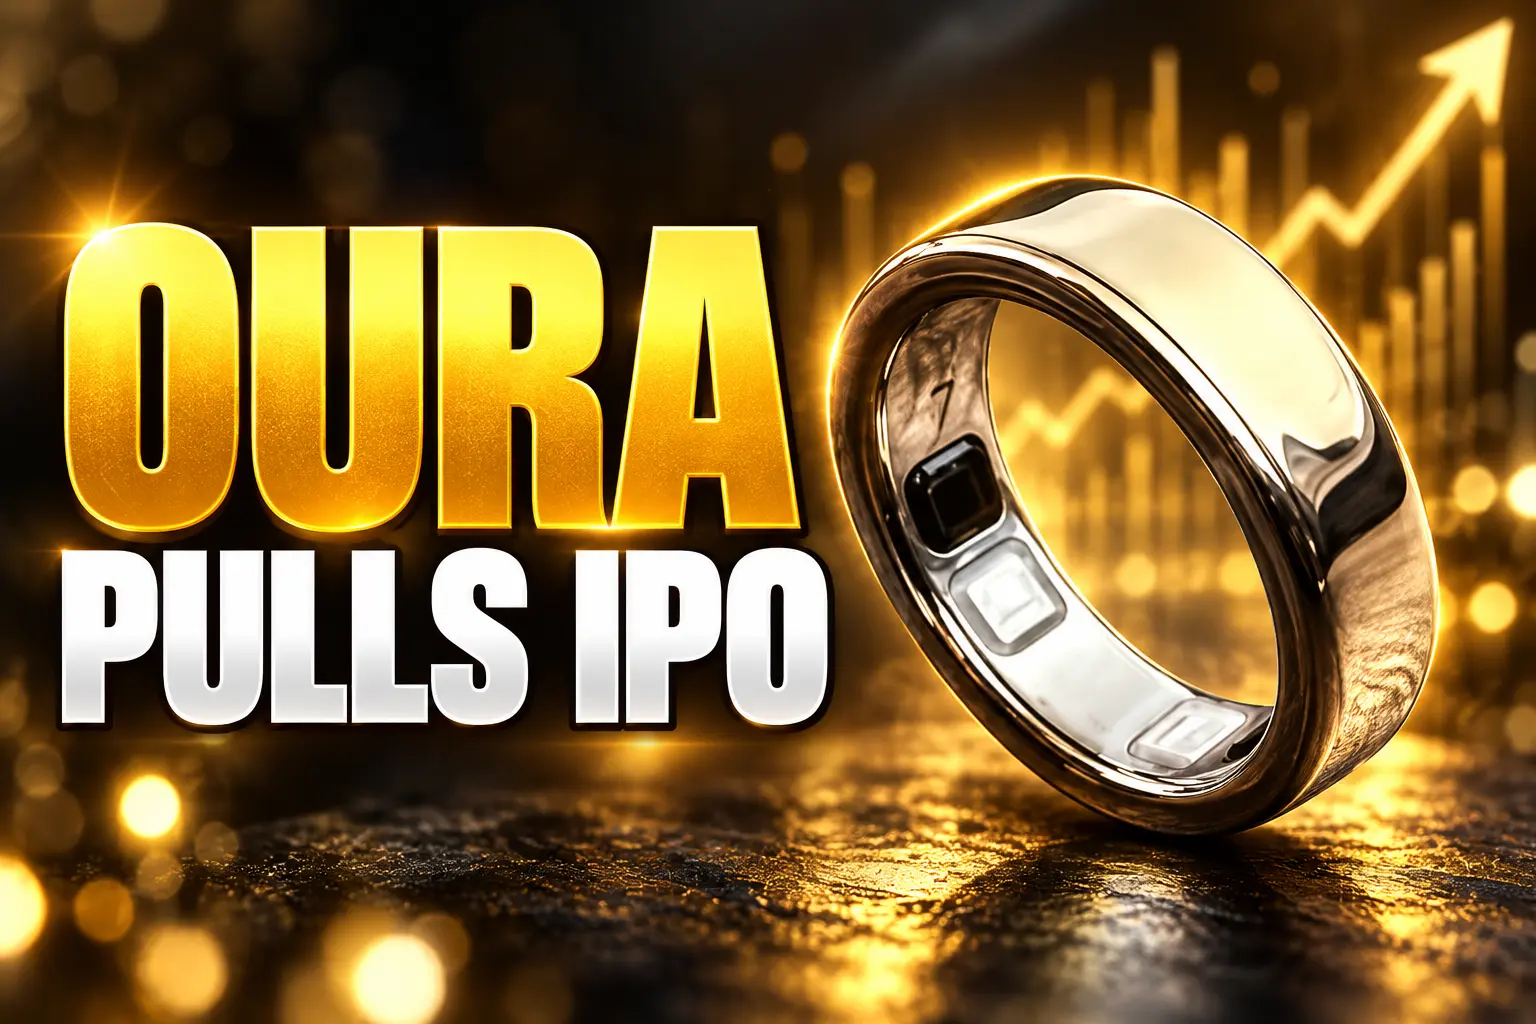
Oura postponed its Nasdaq IPO, a sale that would have paid Forerunner $1.20 billion while leaving the company about $6.2 million.

Oura postponed its Nasdaq IPO on September 29, hours before 50 million shares were due to price between $40 and $44. The sale would have raised up to $2.2 billion. Forerunner Ventures was lined up to sell its entire 9.3% stake.
Chief executive Tom Hale said the company could choose its moment. The amended filing shows why that is easier for Oura than for its backers: existing holders were selling most of the stock, and after an employee tax bill the company would have kept about $6.2 million.
The $1.2 Billion Forerunner Exit
The September 21 amendment did not read like a growth raise. The preliminary prospectus put selling stockholders offering 36.5 million shares in the base deal, against 13.5 million new shares from Oura Inc. That is 73% of the 50 million-share offering. Underwriters also had a 30-day option for another 7.5 million shares, all from those same holders.
Forerunner, the second-largest holder, planned to sell about 28.7 million shares, its full 9.3% position, according to PitchBook’s reading of the filing. At the $42 midpoint that block was worth about $1.20 billion before fees, or 57.4% of the whole offering. Kirsten Green and Eurie Kim, a director, are the managing members of the Forerunner vehicles that hold the stock.
THE OFFERING AT $42
| Party | Shares in the base deal | Proceeds at $42 |
|---|---|---|
| Oura (new shares) | 13.5 million | $567 million before fees |
| All selling shareholders | 36.5 million | $1.53 billion |
| Forerunner Ventures | 28.7 million | $1.20 billion |
Forerunner first backed Oura in the March 2020 Series B, when PitchBook put the company’s value at $725.3 million. It had already taken some cash off the table. The prospectus describes a $65.0 million share repurchase in February, when Oura Health Oy bought 1,617,721 Series B shares from Forerunner-affiliated funds at $40.18 each. The IPO was the rest of the door.
Oura Would Have Kept About $6.2 Million
At $42, Oura estimated net proceeds of $532.6 million after fees, on $567 million of gross proceeds from its 13.5 million new shares. It would have received nothing from the secondary sale. It had applied to list on the Nasdaq Global Select Market under the ticker OURA, with Goldman Sachs, Morgan Stanley, and J.P. Morgan among the bookrunners.
Almost all of that net cash had a named job. The company said it would use about $526.4 million for tax withholding on restricted stock that would vest at the listing, a process the filing calls the RSU Net Settlement. Subtract that tax from the $532.6 million net and about $6.2 million remains for product work, working capital, and other corporate uses.
The same settlement would have booked about $160.0 million of stock-based pay as an expense. Eli Lilly and Company had indicated interest in buying up to $100.0 million of stock in the deal, and funds tied to Dragoneer Investment Group had indicated up to $300.0 million. Those indications were not binding. Lilly also held a $50.0 million SAFE that would have converted into 1,190,476 shares at $42, immediately before closing.
On the 320.9 million shares that would have been outstanding after the deal, the $42 midpoint implied a value of about $13.5 billion. That sat above the roughly $11 billion mark from the October 2025 round, when Fidelity led a $900 million raise, and well above the $5.2 billion value from less than a year before that. Public buyers were being asked to pay that price into a book that was mostly an exit.
Why the Listing Was Built Around Staff Taxes
Oura wanted the listing cash for the tax bill so it would not tap the $371.8 million of cash it held on June 30. Restricted shares for staff would have vested when the company went public. The company would withhold stock to cover the tax, then send cash to the tax authorities. Without a listing, that vest does not happen on that trigger, and the $526.4 million transfer does not come due.
That is a clean outcome for the balance sheet and a stalled one for the people on the grants. Renaissance Capital’s IPO profile listed 1,350 employees at the filing. Any of them who were counting on listing-day liquidity, and any shareholder who needed a public market to sell, now wait. Hale’s statement named employees and investors in the same breath as the people for whom Oura still wants “an extraordinary IPO.”
The company also had debt alongside that cash. Long-term debt was $380.1 million as of June 30, including about $375.0 million drawn on a $525.0 million revolving credit line with J.P. Morgan that matures on June 4, 2029. Another $245.0 million of commitments on that line would have opened only after the offering closed. The pause leaves that extra capacity on the table too.
Fidelity Held While Lifeline Sold a Third
The selling list was short at the top and mixed below it. PitchBook’s tally of the amended S-1 is the source for the holder-level split among the named funds.
WHO WAS SELLING AND WHO WAS NOT
- Forerunner Ventures: Selling the entire 9.3% stake, about 28.7 million shares, after the $65.0 million buyback earlier in 2026.
- Lifeline Ventures: Selling about one third of its holding, nearly 7 million shares, worth about $292 million at $42. Timo Ahopelto, a director, is a founding partner. Lifeline led the 2015 seed round at a value of about $6.1 million.
- Elysian Park Ventures: The Los Angeles Dodgers’ investing arm, a 2021 Series C backer at a $900 million value, selling 61.5% of its stake, worth about $36.6 million at the midpoint.
- Fidelity: Largest holder at 10.9%, selling no shares. Temasek, Iconiq Capital, and Atreides also appeared as large holders taking little or nothing off the table.
That split is the political fact inside the prospectus. Early funds that entered at seed and Series B prices wanted cash. The late-stage lead that set the $11 billion mark in 2025 was willing to stay paper-rich. Public accounts that bought the book would have been standing in for Forerunner, not funding a factory.
The $40 to $44 Range Did Not Clear
Oura opened the roadshow on September 21 and pulled the deal eight days later, before the registration statement was declared effective. Shares had been set to price on the evening of September 29 and to start trading on September 30. The company said it was delaying because of uncertainty in the IPO market, and that it was doing so despite strong demand, with the business stronger than when the roadshow began.
Our mission is to empower people to live healthier, longer, and an IPO is just one step in our journey. We aim to deliver an extraordinary IPO for our employees and investors and we have the luxury of choosing our moment. In the meantime, we will execute against the opportunities ahead.
Tom Hale, chief executive, company statement, September 29, 2026
People approached about buying the stock walked away from the asking price, according to people familiar with those talks. Shares were also described as tracking toward the bottom of the $40 to $44 range. A book that is 73% secondary is a harder sale when the range already looks rich, because new money is not building the company so much as buying out funds.
WHERE EXPERTS DISAGREE
- Market tone: Matthew Kennedy, senior strategist at Renaissance Capital, said a string of three or four postponements in a row tells you something about the market, and that you cannot treat all of them as company-specific problems.
- A changed window: Samuel Kerr, global head of equity capital markets at Mergermarket, said the IPO market is very different from the one desks had in mind a few weeks earlier.
- This book: The filing’s own mix, a full Forerunner exit and about $6.2 million left for Oura, gave buyers a separate reason to wait even if rates were the backdrop.
If the company files again, a 100% sale of a 9.3% stake will be a heavier ask than a smaller secondary. Hale can wait because the operating company did not need the cash. Forerunner’s remaining path to cash is a later listing, a later buyback, or a later private sale, none of which were priced on September 29.
The Ring Business Can Fund a Longer Wait
The delay statement said Oura now has 5.7 million paying members, up from 5.0 million at the end of June, and that it expects fiscal 2026 revenue to rise 90% from $907.9 million. Fiscal 2026 ends September 30. Ring 5, it said, has been received well.
OURA IN THE NINE MONTHS TO JUNE 30
- Sales: Revenue was $1,214.5 million, up 74% from $697.6 million, after $907.9 million in fiscal 2025, which was up 123% from $406.8 million in fiscal 2024.
- Mix: Hardware brought in $974.0 million. Membership brought in $240.5 million, up 121%, about 20% of sales, at an 89% gross margin. Group gross margin was 55%.
- Profit: Net income was $60.8 million, against $1.6 million a year earlier. Adjusted EBITDA was $106.7 million.
- Use: Paid members wore the ring a median of about 23 hours a day in the third fiscal quarter. Twelve-month paid-member retention was about 85% across 56 markets, on nearly 42 billion hours of stored biometric data.
The company sold 3.1 million rings in those nine months, against 1.8 million a year earlier. It began shipping the Oura Ring 5, 40 percent smaller than Ring 4, on June 4, so that hardware line includes about one month of the new model. Black and Silver list at $399, and Gold, Stealth, Brushed Silver, and Deep Rose list at $499. Membership is $5.99 a month or $69.99 a year in the United States.
Hardware is still about 80% of sales, so the story public buyers were offered is that the subscription keeps compounding after the ring is sold. Oura is profitable on that mix, with $371.8 million of cash, and Hale is using that to argue that a listing is optional. The people for whom it was not optional were the funds in the selling group and the staff whose grants were tied to the listing date.
Pulled Listings Piled Up in Late September
Oura would have been the first large U.S. IPO of the autumn window after the summer lull. It arrived in a week when other issuers were already stepping back, a pattern Renaissance Capital has been counting across sectors, not only consumer hardware.
THE ROAD TO THE PULLED LISTING
- September 3, 2026: Oura files its S-1 to list on Nasdaq as OURA, without a price range.
- September 21, 2026: An amended filing sets 50 million shares at $40 to $44 and starts an eight-day roadshow. Bamboo Insurance had postponed on September 22; Amaero postponed later that week.
- September 25, 2026: Holtec Nuclear withdraws its IPO, citing market conditions.
- September 29, 2026: Oura postpones hours before pricing. Renaissance Capital’s tally of deals of at least $50 million reaches four in a week and seven in the third quarter, against four in the second quarter and three in the first.
Kennedy’s point about a string of delays is the market half of the story, and the prospectus is the company half. Bond yields at 19-year highs and fresh doubt about heavy AI spending have made growth multiples harder to defend, which is a problem for a book that needed buyers to pay $40 to $44 so Forerunner could leave. Hale still has a ring that people wear about 23 hours a day and a membership base the company now puts at 5.7 million. Forerunner still holds the 9.3%, the grants that would have vested at listing remain unvested for that event, and Oura has not set a new date.
Disclaimer: This article is news reporting and analysis of a postponed share sale and is for information only. It is not investment advice, a solicitation to buy or sell any security, or a recommendation on Oura or any other company. Readers should consult a licensed financial adviser or securities professional before making any investment decision. Share counts, prices, proceeds, ownership stakes, and listing plans come from the company’s registration statement and public statements as of the dates given and may change if Oura files again or revises its terms.

Capcom Builds an AI-Era Engine and Leaves the Art Human

NASA Funds Starliner Again Because Dragon Is Being Retired

Bangkok Drowned in Rain After Preparing for a River

XRP Asia Opens in Seoul After Korean Rails Went Live

Nike’s Pace Overhaul Pushes the Repair Into 2029

Microsoft 365 Auth Fault Took Down Exchange and Teams

Xbox Caps Game Pass Cloud Gaming at 15 Hours

Squishy Dumpling Toys Recalled After Hiding Illegal Water Beads

IFA 2026’s Weird Gadgets Are Building a Sensor Home

Tesla Puts Its Wheel-Free Cybercab on Austin Streets
-
 NEWS1 month ago
Microsoft 365 Auth Fault Took Down Exchange and Teams
-
 GAMING4 weeks ago
Xbox Caps Game Pass Cloud Gaming at 15 Hours
-
 AUTO1 month ago
Tesla Puts Its Wheel-Free Cybercab on Austin Streets
-
 LIFESTYLE1 month ago
Squishy Dumpling Toys Recalled After Hiding Illegal Water Beads
-
 BUSINESS1 month ago
ChargePoint Stock Rally Prices Wilmer’s Three-Year Cash Plan
-
 NEWS1 month ago
IFA 2026’s Weird Gadgets Are Building a Sensor Home
-
 BUSINESS1 month ago
Diesel Breaks Its Record as the White House Claims Credit
-
 NEWS4 weeks ago
OpenAI Unveils GPT-6 Astra With a Critical Cyber Label